Landscaper Insurance
Insurance support for lawn care, landscaping, snow removal, tree service, and hardscaping businesses
A landscaping business is shaped by the work it takes on.
A company that started with residential lawn care may add commercial maintenance, snow removal, tree work, chemical application, drainage, or hardscaping over time. Each change can affect the way insurance should be reviewed, especially when the business relies on trucks, trailers, mobile equipment, seasonal crews, subcontractors, and contracts with specific insurance requirements.
Your insurance should be built around the work your business performs now, not only the work it performed when the policy was first written.
Why Landscaping Businesses Work With Concklin Insurance Agency
Insurance Review by Service Type
Landscaping insurance should reflect the work your business performs. A lawn care company, snow removal contractor, tree service, and hardscaping business may all fall under the landscaping category, but the insurance needs are not the same.
Concklin Insurance Agency helps you review coverage around your services, equipment, crews, and contracts so the insurance program matches the work your business is doing.
Equipment, Tools, Trucks, and Trailers
Landscaping businesses depend on equipment that moves between shops, trailers, jobsites, and customer properties.
Concklin Insurance Agency helps you review how your tools, mowers, compact equipment, trailers, plows, sprayers, and other equipment are insured while they are stored, transported, and used in the field.
Contract and Commercial Client Review
Commercial clients may have insurance requirements before your crew can begin work.
Concklin Insurance Agency can help you review contract insurance requirements, certificates of insurance, additional insured requests, auto liability, workers' compensation, umbrella limits, and subcontractor insurance questions.
Independent Agency Support
Landscaping insurance quotes can look similar while handling important exposures differently.
As an independent insurance agency, Concklin Insurance Agency can help you compare options from multiple carriers and understand how each option treats your services, equipment, vehicles, snow removal, subcontractors, chemical application, and hardscaping work.
Insurance Built Around the Work Your Landscaping Business Performs
Landscaping insurance should be reviewed around the services you provide, the equipment you use, the people doing the work, and the places where the work happens.
A business that mainly mows lawns may have different exposure than a company that builds retaining walls, plows commercial parking lots, sprays herbicides, trims trees, installs drainage, or maintains large properties year-round.
That is why your insurance review should start with your operations. The work you perform can affect general liability, commercial auto, inland marine, workers' compensation, equipment coverage, pollution-related coverage, professional liability, umbrella limits, and contract requirements.
Lawn Care, Landscaping, and Property Maintenance
Lawn care and landscaping work can include mowing, trimming, planting, pruning, mulching, seasonal cleanup, shrub care, small tree work, fertilization, irrigation, pesticide or herbicide application, and ongoing property maintenance.
These services can create claims involving property damage, customer injuries, damaged lawns, broken windows, damaged fences, irrigation damage, chemical drift, equipment accidents, and employee injuries.
If your business works on residential properties, commercial properties, or municipal spaces, the insurance review should also consider who owns the property and what each contract requires.
Snow and Ice Management
Snow removal should be reviewed as its own exposure because it can create different insurance questions than lawn care or landscaping.
A snow removal contractor may be responsible for plowing lots, clearing sidewalks, salting, de-icing, monitoring weather, responding during storms, documenting service times, and working under contracts that define when and how service is required.
If your business provides snow and ice management, your insurance review should include commercial auto, general liability, umbrella limits, workers' compensation, equipment coverage, subcontractor insurance, and contract requirements.
Hardscaping, Drainage, and Outdoor Construction
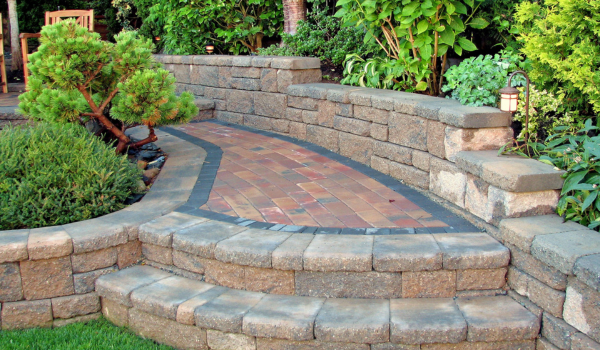
Hardscaping can create more construction-like insurance questions.
Patios, walkways, retaining walls, grading, drainage, irrigation, outdoor kitchens, lighting, stairs, pavers, and other outdoor construction work may involve heavier equipment, design recommendations, subcontractors, underground utilities, completed work, and property damage exposure.
If your business offers hardscaping, the insurance review should address the type of work you perform, whether you provide design or recommendations, how contracts are written, and whether subcontractors are involved.
Special Insurance Considerations for Landscaping Businesses
Equipment, Vehicles, and Jobsite Property
Landscaping businesses depend on equipment that may spend as much time away from the business as it does on the premises.
A mower, trailer, skid steer, plow, sprayer, or set of tools may be loaded, transported, used at a jobsite, stored in a trailer, or left at a customer's property between workdays. That creates different insurance questions than property that stays inside one building.
Commercial property coverage may be limited once equipment leaves your business location, so inland marine or equipment floater coverage should be reviewed. Commercial auto should also be reviewed if your business owns or leases trucks, vans, or other vehicles used to move crews, tools, trailers, and materials between jobs.
Chemical Application and Pollution-Related Exposure
Fertilizers, pesticides, herbicides, weed control products, fuel, and other materials can create claims that may not be handled like ordinary property damage.
A chemical-related claim may involve overspray, drift, runoff, damaged plants, contaminated soil, or allegations that someone became sick after an application. Coverage can depend on what was applied, how it was used, where it traveled, and whether the policy limits or excludes pollution-related claims.
If your business applies, stores, transports, or subcontracts chemical work, this exposure should be reviewed separately. Application records, licensing, product labels, employee training, and storage procedures may also become important if a claim occurs.
Snow and Ice Management
Snow removal can create a different type of exposure than warm-weather landscaping.
A snow and ice claim may focus on when service was required, when your crew arrived, what areas were cleared, whether salt or de-icer was applied, and what conditions existed before and after service. Contract language and documentation can become especially important when a slip-and-fall claim is reported weeks or months after the storm.
If your business provides snow removal, your insurance review should address the work you agreed to perform, the properties you service, the equipment and vehicles used, whether subcontractors are involved, and how service records are maintained.
Underground Property Damage
Digging, grading, planting, trenching, drainage work, irrigation work, and hardscaping can create the possibility of damaging sprinkler lines, drainage systems, buried cables, septic components, gas lines, or other underground property.
These claims can involve repair costs, service interruption, property damage, and questions about whether utilities were marked before work began. If your business performs work that disturbs the ground, underground property damage should be part of the insurance review.
Hardscaping and Completed Work
Hardscaping can create exposure that continues after the crew leaves the jobsite.
A patio may settle. A retaining wall may fail. A drainage project may send water toward a structure. Steps, walkways, outdoor kitchens, lighting, or irrigation work may create questions long after the installation is complete.
These claims can involve completed operations, faulty workmanship, resulting damage, subcontractor work, and professional liability if your business provides design, plans, or recommendations. If your landscaping business performs hardscaping or design-build work, the insurance program should be reviewed around both the installation process and the work after completion.
Tree Work and Height Exposure
Tree trimming and tree removal can create higher-severity claims than many routine landscaping services.
Falling limbs, nearby structures, parked vehicles, fences, power lines, lifts, ladders, and workers at height can all affect the way the work is insured. Even small tree work can become complicated if a branch damages a roof, strikes a vehicle, injures someone, or affects a neighboring property.
If your business performs tree work, the type of work should be clearly reviewed with your insurance agent. Light pruning, ornamental tree care, large tree removal, crane work, and work near power lines may be treated differently by insurance carriers.
Key Insurance Coverages for Landscaping Businesses
A landscaping insurance program should reflect the work your business performs, where that work takes place, the equipment you depend on, the vehicles you operate, the people doing the work, and the contracts you accept.
General Liability
General liability insurance helps protect your business from certain injury and property damage claims involving customers, property owners, pedestrians, vendors, or other third parties.
For landscaping businesses, this may include claims involving damaged property, customer injuries, jobsite accidents, or damage connected to lawn care, landscaping, snow removal, tree work, chemical application, or hardscaping operations.
Pollution Liability
Pollution liability may be needed when a business applies, stores, transports, or subcontracts work involving pesticides, herbicides, fertilizers, fuel, or other materials that could create pollution-related claims.
General liability policies may limit or exclude certain pollution claims, so chemical and environmental exposure should be discussed separately.
Commercial Umbrella
Commercial umbrella coverage can provide additional liability limits above certain underlying policies, such as general liability or commercial auto.
For landscaping businesses, higher limits may be important when the business has significant vehicle use, trailers, snow removal, commercial contracts, subcontractors, hardscaping, chemical application, tree work, or higher-severity property damage and injury exposures.
Cyber Liability
If your landscaping business uses digital payment systems, payroll platforms, scheduling tools, customer records, vendor accounts, online portals, or electronic communication, a cyber event can affect payments, payroll, customer information, vendor access, and daily work scheduling.
Commercial Property
Commercial property coverage helps protect property at your business location.
This may include buildings, office contents, shop equipment, stored materials, supplies, and certain equipment kept at the premises. Tools and equipment that regularly leave the premises may also need inland marine or equipment floater coverage.
Workers' Compensation
Workers' compensation helps protect employees and the business when someone is injured on the job.
For landscaping businesses, payroll, job classifications, seasonal workers, snow removal, tree work, hardscaping, chemical application, and the type of work employees perform can all affect workers' compensation.
Employment Practices Liability
Employment practices liability insurance can help protect your business from certain employee-related claims, such as discrimination, harassment, wrongful termination, or retaliation.
For landscaping businesses, employment-related exposure may involve hiring, seasonal workers, supervision, discipline, termination, wage-and-hour concerns, or claims involving managers or crew leaders.
Inland Marine and Equipment Floater
Inland marine or equipment floater coverage helps address tools and equipment that move between jobsites.
This coverage is important because commercial property coverage can be limited once equipment leaves your main business location. The policy should account for how equipment is stored, transported, scheduled, valued, and protected while it is away from the shop.
Commercial Auto
Commercial auto coverage applies when your business owns or leases trucks, vans, plow vehicles, or other vehicles used for business purposes.
Landscaping businesses often depend on vehicles to move crews, materials, trailers, and equipment between jobs. The policy should match how those vehicles are used, who drives them, what they tow, whether snow removal is included, and what contract requirements apply.
Hired and Non-Owned Auto
Hired and non-owned auto coverage applies when employees use personal, rented, borrowed, or non-owned vehicles for work-related driving.
This may include estimates, supply runs, jobsite visits, errands, snow removal support, or other business trips. Hired and non-owned auto helps address liability exposure for the business, but it does not replace the employee's personal auto policy.
Professional Liability
Professional liability can be important when a business provides design, consulting, plans, drainage recommendations, grading advice, retaining wall recommendations, irrigation design, or other professional services.
This coverage is especially relevant for hardscaping, drainage, and design-build landscaping work because a claim may involve advice, plans, or recommendations rather than only physical damage during the job.
What is Inland Marine Insurance and Why Your Business Might Need It
Despite its name, inland marine insurance is not limited to boats, trains, or shipping companies. It is a flexible type of business insurance designed to cover certain property, tools, and equipment while they are being transported, used away from your primary location, or temporarily stored elsewhere.
Here is a closer look at what inland marine insurance can cover, when it may apply, and which businesses may need it
Frequently Asked Questions
What insurance does a landscaping business need?
The insurance a landscaping business needs depends on the services provided, equipment used, vehicles operated, employees, subcontractors, contracts, and whether the business performs lawn care, snow removal, tree work, chemical application, hardscaping, or design work.
Common coverages may include general liability, commercial auto, hired and non-owned auto, inland marine or equipment floater, workers' compensation, commercial property, commercial umbrella, contractors pollution liability, professional liability, employment practices liability, and cyber liability.
Does my landscaping insurance need to change if I also do snow removal?
Yes, snow removal should be reviewed separately because it creates different risks than lawn care or landscaping.
Snow and ice work may involve plowing, salting, sidewalk clearing, commercial lots, subcontractors, weather monitoring, service logs, late-night driving, and slip-and-fall claims. Contracts may also include specific insurance requirements or documentation expectations.
If you add snow removal, review your general liability, commercial auto, umbrella, workers' compensation, hired and non-owned auto, equipment coverage, subcontractor requirements, and snow removal contract language.
What insurance do I need if I offer hardscaping, patios, retaining walls, or drainage work?
Hardscaping and outdoor construction work should be reviewed differently than basic lawn maintenance.
Patios, retaining walls, drainage, grading, irrigation, outdoor kitchens, lighting, and similar work can create claims involving property damage, completed operations, faulty workmanship, underground utilities, design recommendations, and subcontractor work.
Your insurance review should include general liability, completed operations, professional liability if you provide design or recommendations, inland marine, commercial auto, workers' compensation, umbrella coverage, subcontractor insurance, and contract requirements.
What happens if my mower, trailer, skid steer, or tools are stolen from a jobsite?
Coverage depends on how your policy protects equipment away from your main business location.
Commercial property coverage may be limited once tools and equipment leave the premises. Inland marine or equipment floater coverage is often used to insure mobile equipment, tools, trailers, and machinery that move between jobsites.
The policy should be reviewed for scheduled equipment, unscheduled tools, theft limitations, deductibles, storage requirements, and how equipment values are documented.
Does my insurance cover equipment while it is being transported between jobs?
It depends on the policy and the equipment involved.
Landscaping equipment may need inland marine or equipment floater coverage when it is transported between jobs, stored in a trailer, parked at a jobsite, or used away from your business location.
You should also review commercial auto coverage because an accident involving a truck or trailer can raise different insurance questions than theft or damage to the equipment being transported.
Do I need commercial auto insurance for my landscaping trucks and trailers?
Commercial auto coverage should be reviewed if your business owns or leases trucks, vans, or other vehicles used for business purposes.
Trailers and attached equipment should also be reviewed so you understand how liability and physical damage may be handled.
What happens if one of my employees hits a parked car with a truck, trailer, or mower?
The claim may involve more than one coverage, depending on what happened and what equipment was involved.
If the accident involved a business-owned vehicle, commercial auto may respond. If the employee was using a personal vehicle for work, hired and non-owned auto may need to be reviewed. If the damage involved a mower, trailer, or other equipment, the claim may also raise general liability, equipment, or property coverage questions.
Your agent can help determine which policy may apply and how the claim should be reported.
Am I covered if I damage a customer's fence, driveway, irrigation system, or landscaping?
Property damage claims may involve general liability coverage, but coverage depends on the policy and the facts of the claim.
A landscaping business may face claims involving damaged fences, driveways, sprinkler heads, irrigation systems, windows, lawns, plants, hardscaping, vehicles, or neighboring property.
The type of work being performed, what caused the damage, whether the work was completed, and any exclusions in the policy can affect how the claim is handled.
What happens if we hit an underground utility, sprinkler line, or drainage system?
Hitting an underground utility, sprinkler line, irrigation line, or drainage system can create property damage, repair costs, service interruption, and liability questions.
Coverage depends on the policy, the work being performed, the cause of the damage, whether utilities were marked, and whether exclusions apply.
If your business digs, grades, installs irrigation, builds retaining walls, plants trees, or performs drainage work, underground property damage exposure should be reviewed carefully.
Do I need workers' compensation for a small landscaping crew?
Workers' compensation should be reviewed if your landscaping business has employees.
Landscaping work can involve cuts, lifting injuries, falls, heat illness, equipment injuries, vehicle accidents, chemical exposure, and injuries during snow removal or hardscaping work.
Payroll, job classifications, seasonal employees, part-time workers, subcontractors, and the type of work performed can all affect workers' compensation.
Do I need different insurance if I use subcontractors?
Subcontractors can change your insurance needs.
If you use subcontractors review whether they carry their own insurance, whether they should name your business as an additional insured, and whether your policy treats subcontracted work differently.
Contracts, certificates of insurance, workers' compensation, general liability, auto liability, and umbrella limits should all be reviewed before subcontractors begin work.
What insurance do commercial clients, HOAs, or condo associations usually want from landscapers?
Commercial clients, HOAs, condo associations, property managers, municipalities, and general contractors may require proof of insurance before work begins.
Requirements may include general liability, workers' compensation, commercial auto, umbrella coverage, additional insured status, waiver of subrogation, and specific limits.
Snow removal, hardscaping, tree work, and chemical application may create additional contract requirements, so review those requests with your insurance agent before signing.
Does landscaping insurance cover pesticide, herbicide, or fertilizer claims?
Pesticide, herbicide, and fertilizer claims should be reviewed carefully because coverage depends on the policy.
Claims may involve chemical drift, overspray, damaged plants, contaminated soil, water runoff, customer illness allegations, or damage to neighboring property.
Some general liability policies may limit or exclude pollution-related claims. If your business applies, stores, transports, or subcontracts chemical work, pollution liability or other coverage may need to be reviewed.
What should I review before signing a snow removal contract?
Before signing a snow removal contract, review the scope of work, service triggers, response times, documentation requirements, indemnity language, insurance requirements, additional insured requests, waiver of subrogation, subcontractor rules, and hold harmless provisions.
Snow removal contracts can affect how claims are handled after a slip-and-fall allegation or property damage claim.
Your insurance agent can help you understand whether the insurance requirements match your current coverage.
Does my insurance cover faulty workmanship or mistakes in hardscaping work?
Faulty workmanship can be complicated and may not be covered the way a business owner expects.
General liability may respond to certain resulting property damage claims, but it may not pay to redo defective work or correct poor workmanship. Exclusions, completed operations coverage, subcontractor work, and the type of damage all matter.
If your business installs patios, retaining walls, drainage, irrigation, or other hardscape features, review how your policy treats completed work, faulty workmanship, and resulting damage.
Do I need professional liability if I design patios, drainage, retaining walls, or outdoor spaces?
Professional liability should be reviewed if your business provides design, consulting, plans, recommendations, grading advice, drainage recommendations, retaining wall design, irrigation design, or other professional services.
General liability is not designed to cover every financial loss tied to design advice or professional recommendations.
If customers rely on your plans or recommendations, review whether professional liability should be part of your insurance program.
How do I compare landscaping insurance quotes?
When comparing landscaping insurance quotes, look closely at how each option treats the work your business performs.
A quote may look competitive but exclude snow removal, limit subcontracted work, underinsure equipment, miss hired and non-owned auto, exclude pollution-related claims, or fail to address hardscaping and professional liability concerns.
An independent insurance agent, like Concklin Insurance Agency, can help you compare options from multiple carriers so you understand how each quote fits your services, contracts, equipment, vehicles, employees, and jobsite exposures.
Request a Quote
Insurance Insights and Risk Management Guidance
Our blog articles help you stay informed and make more confident insurance decisions.


Talk to one of our agents
Client Resources
Client Portal
The Zywave portal gives Concklin clients access to professionally written insurance, HR, safety, compliance, and risk management resources. Content can be tailored by industry, state, and preference, with email updates available when new resources are added. Contact your Concklin representative with any questions.
Client Advocacy
Independent agents can serve as trusted advisors before and after coverage is bound. If a claim occurs, we can help you understand the process, communicate with the carrier, and gather information needed for the claim. Being in your corner means being there every step of the way, from helping you decide if a claim should be filed to talking with claims adjusters, the wellbeing of our clients is our number one priority.
Cyber Resources
Cyber threats can create serious costs for small businesses, including breach response, forensic work, customer notifications, legal expenses, and reputational damage. Concklin Insurance Agency offers cyber liability insurance, along with resources to help business owners better understand and reduce their cyber risk.
Request a Landscaping Insurance Quote
Your landscaping business may involve equipment, trucks, trailers, seasonal work, employees, subcontractors, contracts, snow removal, chemical application, hardscaping, and jobsite property damage exposure.
Concklin Insurance Agency can help you review your coverage, compare options, and build an insurance program around the work your business performs.